Pull up five different real estate data sites and search "West Village home prices" this month, and you will get five different answers about the same three months of 2026. One shows prices down more than 50 percent year over year. Another shows them down 17 percent, but with the price per square foot actually up. A third shows values down closer to 22 percent. A fourth, tracking co-ops specifically, shows prices up 24 percent. All of them are describing the same 15 blocks of Manhattan during the same stretch of this year.
If you are shopping in the West Village right now and trying to figure out whether you are catching a dip or walking into a runaway market, this is not a data problem you can solve by finding the "right" website. It is a structural feature of a neighborhood where different trackers can't even agree on how many homes changed hands in the same month, let alone at what price, and where one $70 million townhouse trade can move a median more than a hundred well-priced co-ops moving in the opposite direction. Understanding why the headline number is this unstable matters more than memorizing any single figure, because the number you should actually be underwriting against is a different one entirely, and it barely moves at all.
Why 32 sales can tell five different stories
Start with what a small, thin market does to a statistic like "median sale price." In May 2026, one widely used property data service counted 32 closed sales in the West Village and reported the median at $1.2 million, a drop of 52.5 percent from the same month a year earlier. Over that same three month window, a national brokerage portal counted 66 closings and put the median at $1.5 million, down a comparatively modest 17.1 percent, while noting price per square foot was actually up 33.9 percent year over year. A third portal put the typical home value down 21.9 percent as of late June.
None of these are wrong. They are measuring different things. The first source's own breakdown shows why: in that same May window, the median house sale price jumped 438.5 percent to $70 million on what was likely a single trophy townhouse transaction, while the median co-op sale fell 28.8 percent to $825,000 and the median condo sale rose 16.9 percent to $4.3 million. Blend three property types with wildly different price points and a sample size in the dozens, and the "median" for the month is really just a description of which mix of townhouse, co-op, and condo happened to close, not a signal about whether the neighborhood got more or less expensive.
This is the trap for anyone using a portal's headline number as a proxy for market direction. A softer co-op month next to a strong condo closing can make the whole neighborhood look like it swung 20 or 30 points in either direction, when the underlying pricing for a given apartment type barely moved. If you are comparing an offer against "the market," ask what sold, not just what the median said.
The only supply number that doesn't reset every quarter
While the median bounces around with whatever closed that month, the real driver of West Village pricing has stayed remarkably fixed for more than half a century, and it has nothing to do with buyer sentiment.
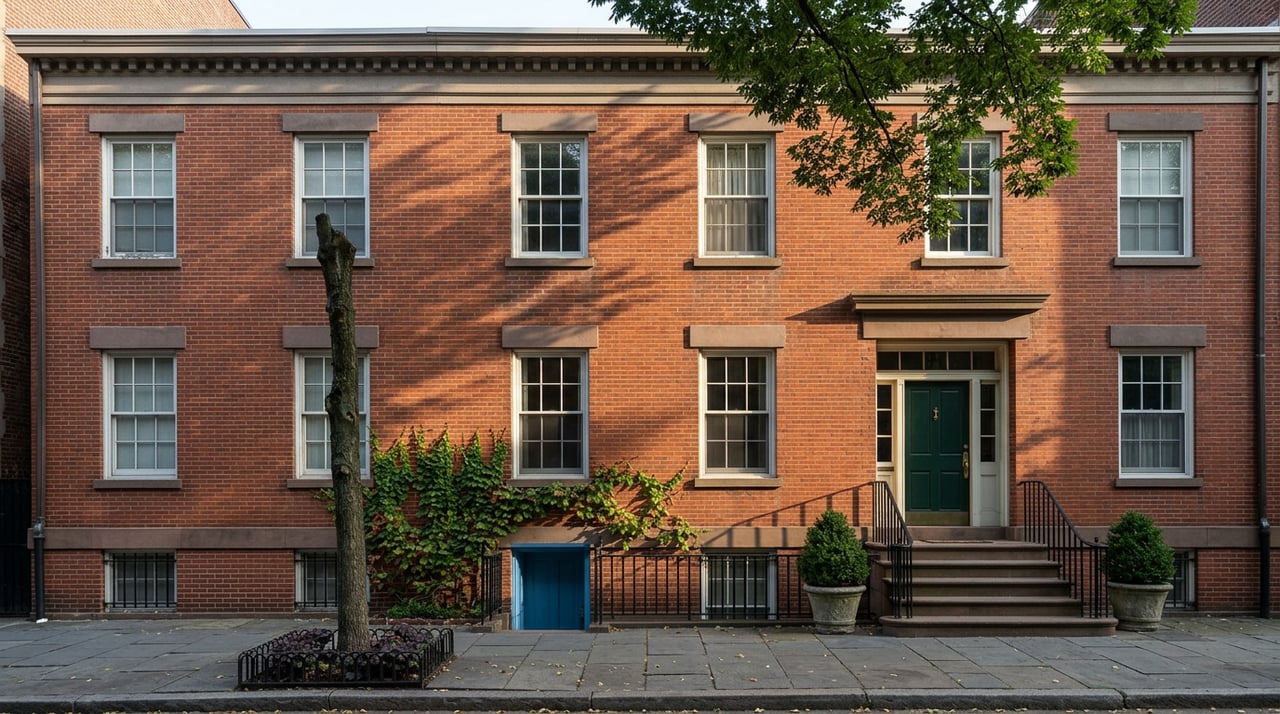
The Landmarks Preservation Commission designated the Greenwich Village Historic District in April 1969, protecting roughly 2,050 buildings and making it, at the time, the largest historic district in the city. That boundary did not move again for decades. The first expansion did not come until 2006, when a campaign by preservation advocates secured landmark status for part of the Far West Village and the Weehawken Street area, protections Jane Jacobs had pushed for as early as 1963. The Gansevoort Market area, at the neighborhood's northern edge, followed a separate track: the city designated a Gansevoort Market Historic District in 2003, and a larger version was added to the State and National Register in 2007.
Add it up and roughly 80 percent of the West Village now sits inside one of these protected districts. Inside that boundary, demolition is effectively off the table, new construction is capped in scale, and any exterior alteration needs Landmarks Preservation Commission sign-off. You can see the actual boundary on the Landmarks Preservation Commission's own district map, which still traces the same 1969 lines with the later extensions layered in. That map, not this month's median, is the number that actually explains why inventory here behaves differently than almost anywhere else in Manhattan. It is a fixed constraint, not a cyclical one, and it does not reset when rates move or a stock index has a bad quarter.
Three pricing bands, not one blended median
Because the neighborhood's housing stock is genuinely three different products dressed in the same zip code, a single blended median was never going to be useful for underwriting an actual offer. The bands worth knowing:
- Townhouse and brownstone co-op conversions, the one or two bedroom units carved out of subdivided row houses with exposed brick and original mantels, trade in the range of $1,500 to $2,500 per square foot depending on condition and floor.
- Prewar co-ops in larger walk-up and elevator buildings, the more conventional layouts with doorman infrastructure in the full-service buildings, run from roughly $1,200 to $2,000 per square foot.
- Condos, the scarcest product type in the neighborhood, trade from $2,500 up to $4,000 or more per square foot, with waterfront trophy addresses like 150 Charles, 160 Leroy, and Superior Ink pricing well above that range.
When you see a neighborhood median move, ask which of these three buckets actually shifted. A quiet month for condo closings and a busy one for brownstone co-ops will drag the blended number down even if nothing changed inside either category.
A new line item for the condo buyer specifically
There is one more thing now in effect that could reshape how that condo band behaves, and it is worth knowing before you make an offer on one.
New York's fiscal year 2026-27 state budget included a pied-a-terre tax, an annual surcharge on high-value residential property that is not the owner's primary residence. According to Holland & Knight, it took effect July 1, 2026, and runs through June 30, 2031 unless extended. According to Kaufman Rossin, during its first phase, condo and co-op units with a city-assessed value of $1 million or more face a surcharge between 4 and 6.5 percent, while one-to-three family homes valued at $5 million or more face 0.8 to 1.3 percent. The city's Department of Finance began mailing initial determination notices in July, with owners notified by August 30 and, per updated guidance, until September 18 to file an exemption.
There is a real wrinkle here that matters specifically for co-op shoppers: Reed Corp. explains that the city currently values individually owned co-op units using an income-capitalization method built for rental buildings, which can produce an assessed value far below what a unit actually sold for.
West Village international buyers have historically leaned toward condos over co-ops precisely because condo boards are more flexible on foreign-buyer documentation and pied-a-terre use. That is exactly the buyer pool this new surcharge targets. It will not show up in a portal's median sale price this year, but it is a real, non-trivial addition to the carrying cost calculation for anyone weighing a scarce, high-price condo against a co-op.
What to actually track
If you are shopping in the West Village, stop trying to reconcile five conflicting median price headlines and start asking three narrower questions instead. What did comparable units in your specific product type, co-op, condo, or townhouse, actually close for in the last 90 days. Is the building you are considering inside the 1969 historic district boundary or one of its later extensions, because that answers whether its scarcity is durable. And if you are looking at a condo as a non-primary residence, has anyone modeled the pied-a-terre surcharge against your specific purchase price.
Those three answers will tell you more about your actual deal than any blended neighborhood median ever could.
FAQ
Why do different real estate sites report such different price changes for the same neighborhood and month? Small monthly sale counts mean the mix of what closed, by property type and price tier, can swing a blended median 20 to 50 points without the underlying market moving at all. Sites that separate co-ops, condos, and houses will show a different picture than ones reporting a single blended figure.
Does the historic district mean nothing new will ever be built in the West Village? Inside the Greenwich Village Historic District and its extensions, exterior alterations need Landmarks Preservation Commission approval and large-scale new construction is effectively off the table.
Does the pied-a-terre tax apply the same way to co-ops and condos? Both face the same rate bracket in Phase 1, but co-ops are currently assessed using a rental-building valuation method.
If you are trying to make sense of what a specific West Village building or block is actually worth right now, rather than what a blended median says it might be worth, Varun Sharma can walk you through the comps that matter for your product type and get you a clear read before you write an offer.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.